ABA Banking Journal: State attorneys general express support FCC Robocall Mitigation Database proposal
November 10, 2026
A coalition of 49 state attorneys general expressed support for the Federal Communications Commission’s Robocall Mitigation Database proposal while urging the agency to require better vetting of the information that telecommunications providers submit.
All voice service providers must register in the RMD and submit information on their practices to prevent the transmission of illegal calls over their networks. The FCC is proposing to bolster the database by, among other things, requiring entities to file more specific information on their efforts to prevent the transmission of illegal calls, creating a more robust pre-screening process for RMD submissions, and limiting exemptions from filing requirements.
The American Bankers Association and 10 other associations recently endorsed the FCC proposal while offering their own recommendations to strengthen it. In a letter, the attorneys general said they supported strengthening the database but believed that the FCC could go further. To start, the commission should ensure that all information available to the public through the RMD is thoroughly reviewed and determined to be accurate and complete, they said. The attorneys general also encouraged the FCC to use technological tools to vet new entrants to the RMD and determine their relationships with bad or questionable actors.
In addition, the attorneys general encouraged the adoption of a “knew or should have known” standard “to heighten accountability of those providers that choose to look the other way and not become familiar with their obligations,” and take other steps to avoid repeat offenders.
The attorneys general “endorse those measures that would allow the RMD to move closer to becoming the flagship tool envisioned by the FCC: a trustworthy resource of fully vetted, accurate, and complete filings that can serve as the centerpiece of both law enforcement’s and industry’s common fight against illegal calls,” they said.
Politico: AI agents scramble banks’ fight with fintechs
11/11/26 | Michael Stratford and Aiden Reiter
AI is crashing into the long-running fight between banks and financial technology companies.
A Consumer Financial Protection Bureau rule now before the White House Budget Office about who controls consumers’ financial data could be a vehicle to regulate the new crop of AI agents roaming through the financial system, according to bank lobbyists familiar with the discussions.
“We are having conversations with regulators, technology firms and others,” Lindsey Johnson, president and CEO of the Consumer Bankers Association told MM. “Consumers could be well served by the CFPB’s supervision and oversight of AI agents and companies.”
Fintech advocates, meanwhile, are telling the administration that the technology makes strong data-sharing protections more urgent, and they’re warning against letting banks use security concerns to block competing services. The stakes for the banks are huge. The new agents could help consumers compare borrowing costs or find better savings rates quickly, with the potential to undercut the deposit system on which banks rely.
JPMorgan Chase CEO Jamie Dimon warned about “rogue agents” on last month’s earnings call and has urged bank customers to avoid giving their passwords to Meta, which runs the popular AI agent Muse. PNC CEO Bill Demchak blasted technology companies as “kids in a room with a new toy” last month, warning about agents transacting without human oversight. The AI debate adds fuel to the longstanding fight between banks and fintechs over the rule. A key sticking point for years has been over whether banks can charge for data access. Banks say secure systems cost money; fintechs say fees could stifle competition and raise prices.
Steve Boms, executive director of the Financial Data and Technology Association of North America, acknowledged the risks from AI agents but said the fight is also about whether banks can shut out rivals.
“It’s fundamentally about: should a consumer have the ability to choose a non-bank or another bank, third-party provider, to provide a service that competes directly with something my bank may or may not offer,” he said.
A 2024 Biden administration rule prohibited those fees. The Trump administration initially backed banks’ push to invalidate it in court. But after crypto executives joined fintechs and retailers in lobbying the White House last year, the administration pivoted to a rewrite. The Biden rule remains blocked in court. Details of the rule now at the White House have not been released. With the CFPB in limbo as it waits for the confirmation of a new director, the path ahead for the rule remains unclear. And, if the agency’s new director is willing to pull back the rule currently sitting with the White House to address new concerns, the politics could get messier.
“The politics [around the rule] have always been super weird,” said one Washington bank insider, granted anonymity to discuss matters candidly. “And AI only complicates things. You now have banks on one side, and potentially fintechs and big AI companies on the other. And consumers and heightened chances of fraud in the middle.”
ABA survey: Consumers happy with credit card options, concerned about rate cap effects
November 12, 2026
Consumers are happy with their credit cards and the benefits they offer, according to the results of a new survey released today by the American Bankers Association.
The survey, conducted for ABA by Morning Consult before the midterm elections, showed that most Americans view the credit card marketplace as highly competitive, and they have concerns about reduced access to credit and other potential harm from policy proposals to cap credit card interest rates.
“Americans view their credit cards as an essential tool to help them navigate daily financial challenges, and they see firsthand the security, choice and convenience that today’s highly competitive marketplace offers,” said Rob Nichols, ABA president and CEO. “Whether it’s fraud protection, financial flexibility or generous rewards programs, the vast majority of consumers recognize and appreciate that their credit card provides very valuable benefits.”
Seventy-seven percent of consumers reported being satisfied with their current credit cards, and 70% said access to a credit card is important for managing household finances. More than two-thirds (67%) said the credit card marketplace is highly competitive and that they have multiple options to choose from when picking a card to best meet their needs.
The leading card benefits consumers identified were fraud and security protection (79%); access to credit in case of emergency (78%); earning rewards (75%); the convenience of not carrying cash (74%); financial flexibility when costs rise (73%); special offers from retailers and brands (69%); help bridging financial gaps between paychecks (66%); and travel benefits (60%).
The survey also gauged consumers’ views on card policy issues. Americans do not want government-imposed price controls on credit cards that restrict access to credit and jeopardize credit card rewards programs, according to the survey’s findings.
Credit card interest rates are not a top economic concern for most Americans, survey findings showed. When asked to pick among several economic issues they would like Congress to prioritize, consumers ranked credit card interest rates near the bottom of the list. Inflation, food and grocery prices, healthcare costs, housing affordability, energy costs, government spending and the deficit, and wages and income growth all ranked well ahead of credit card interest rates as top concerns for consumers.
By nearly a 4-to-1 margin (66% vs. 17%), Americans said a one-size-fits-all credit card interest rate cap ignores that people have different financial situations (vs. only 17% who disagree). By a nearly 2-to-1 margin (55% to 30%) consumers oppose a 10% rate cap if it results in higher annual fees for most cardholders. By a nearly 3-to-1 margin (62% vs. 23%), consumers expressed concern about potential negative impacts on credit scores from account closures or credit line reductions caused by an interest rate cap. By a nearly 5-to-1 margin (70% vs. 15%), consumers said responsible cardholders shouldn’t face higher fees or reduced rewards because of new regulations.
Seventy-five percent of respondents said it is important for Congress to prevent higher annual fees for cardholders (75%) as a result of new regulations, to protect consumers from losing access to credit cards or seeing their credit limits significantly reduced because of new regulations (73%), and to protect people from being pushed toward payday loans or other extremely high-interest lenders as a result of new regulations (73%).
“The survey shows that many consumers recognize the potential harm from a credit card rate cap including reduced access to credit for some of the very people a cap is intended to help,” Nichols said. “Americans are rightly concerned that rate caps would make the affordability challenge worse by limiting the number of people who qualify for credit cards, imposing higher fees for those who do qualify, and forcing more consumers to turn to less regulated, more costly alternatives.”
ABA Banking Journal: Nichols: ABA to lead on tokenization
October 26, 2026
In wide-ranging remarks opening the 2026 American Bankers Association Annual Convention, ABA President and CEO Rob Nichols laid out how the association will position itself to support banks in the digital asset space, particularly through tokenized money, including tokenized deposits and stablecoins.
Among other things, ABA will take on two key roles, Nichols noted. First, ABA will serve as the banking industry’s “on-ramp” to the world of digital assets, through which the association will position itself as a primary source of education, guidance and practical support for banks as they evaluate opportunities around tokenized money. The second role ABA will play is that of a “trusted convener,” which Nichols noted will “bring industry participants together and advocate for fair, equitable access to emerging tokenized money infrastructure.”
“We recognize that many banks are interested in tokenized money, but may lack the resources, expertise, or market visibility available to larger institutions. That’s where ABA can help,” Nichols said. “ABA is actively advancing a strategy around tokenized money that ensures our members have the information and opportunity to embrace innovation where it makes sense and on your terms.” Learn more at aba.com/TokenizedMoney.
CISA News: US Government Partners Urge Hardening Industrial Refrigeration and Cold Chain Monitoring Systems
November 5, 2026
Overview
The Cybersecurity and Infrastructure Security Agency (CISA), Federal Bureau of Investigation (FBI), Health and Human Services (HHS), U.S. Department of Agriculture (USDA), and the Department of Transportation (DoT)—hereafter referred to as “the authoring organizations”—are aware of malicious cyber activity targeting industrial refrigeration and cold chain monitoring systems globally. Organizations in the Healthcare and Public Health, Chemical, Food and Agriculture, and Transportation Systems Sectors widely use these systems, including in refrigerated transport services, for automated and remote monitoring of temperatures, continuous temperature logging, defrost cycle management, and energy optimization.
The authoring organizations urge owners and operators to defend against this activity by using strong authentication, keeping systems updated, identifying any systems that are accessible from the internet, removing unnecessary remote access, and securing any necessary remote access.
Threat
The authoring organizations are aware of malicious cyber actors targeting electronic temperature controllers and commercial refrigeration controllers in retail grocery and cold storage facilities. The actors may exploit vulnerabilities or weaknesses in unpatched or internet-accessible controllers to remotely alter settings and force units into continuous heating and defrost cycles, which can cause widespread inventory loss and equipment hazards.
Specifically, the actors may exploit these flaws through multiple vectors:
Authentication bypass;
Arbitrary code injection; and
Weak configurations.
Upon successful exploitation of the flaws, the actors could achieve the following effects:
Change of temperature, which could:
Affect the service life of the system;
Create a fire hazard;
Cause loss of inventory; or
Indirectly harm consumers if products are consumed after unsafe storage.
Loss of visibility into current temperatures (a denial-of-view condition).
Mitigations
The authoring organizations urge owners and operators to immediately take the following actions. These mitigations align with the Cross-Sector Cybersecurity Performance Goals (CPGs), developed by CISA and the National Institute of Standards and Technology (NIST). The CPGs provide a minimum set of practices and protections that CISA and NIST recommend all organizations implement:
Eliminate public internet exposure: Do not expose control system devices and/or systems, particularly controller panels, to the internet [CPG 3.S]. Should remote access be necessary, protect it by using a firewall or edge device and updating it to the latest version to reduce security vulnerabilities. See CISA’s Internet Exposure Reduction Guidance and Defend the Edge: The Critical Importance of Edge Device Security for additional guidance on securing edge devices.
Isolate operational technology (OT) devices: Create a dedicated OT virtual local area network (VLAN) to separate OT devices from business networks [CPG 3.I].
Restrict access: Define and maintain device and IP address allow listing, limiting access to only those devices and IP addresses authorized to make changes [CPG 3.H].
Have reliable backups: Maintain current backups offsite and offline and test them [CPG 3.O].
Monitor and report: Enable logging [CPG 3.Q] and regularly review logs for unexpected activity.
For OT assets where logs are non-standard or not available, collect network traffic and communications between the assets.
Review setpoint ranges: Define and maintain reasonable setpoint limits for devices operating downstream of controllers to stay within safe ranges and establish alerting for deviations.
Resources
The authoring organizations strongly urge industrial refrigeration and cold chain monitoring system owners and operators to secure remote access to their OT systems. To strengthen system security, owners and operators should review the following resources and implement recommended mitigations:
Name of the submitting company or organization, and a designated point of contact.
Contact HHS via [email protected] or the HHS 24/7 Operations Center at 202-619-7800 for assistance mitigating potential disruptions to the delivery of healthcare resulting from health and medical supply chain impacts.
Disclaimer
The information in this report is being provided “as is” for informational purposes only. The authoring organizations do not endorse any commercial entity, product, company, or service, including any entities, products, or services linked within this document. Any reference to specific commercial entities, products, processes, or services by service mark, trademark, manufacturer, or otherwise, does not constitute or imply endorsement, recommendation, or favor by the authoring organizations.
The South Dakota Bank Directory provides detailed information on all South Dakota banks including addresses, telephone numbers, important contact names and additional pertinent information. The directory also contains information on the SDBA, banking associations, regulatory agencies, endorsed vendors, associate members and South Dakota officials.
All member banks, associate members, and endorsed vendors receive one complimentary copy.
2027 GSBC Scholarships
As a co-sponsor of the Graduate School of Banking at Colorado (GSBC), the SDBA has partnered with GSBC to recognize community banks across South Dakota for their innovative approaches to serving their customers and communities with a nomination-based scholarship.
The scholarship is called the Bolder Banking Scholarship and is an extension of GSBC’s Bolder Banking campaign, which aims to highlight bold leaders in the community banking industry by sharing innovative information and ideas with fellow bankers.
The Bolder Banking Scholarship will afford the SDBA the opportunity to recognize and reward our member banks displaying innovative approaches to banking. GSBC will fund the scholarship for a rising star within the recipient bank to use toward tuition at GSBC’s Annual School Session.
SDBA member banks may nominate themselves or another bank to be a Bolder Banking Scholarship recipient. There is one of these bank-wide scholarships given annually. To submit a Bolder Banking Scholarship nomination for your or another bank displaying innovative, out-of-the-box initiatives, complete the nomination form by February 15, 2027.
The GSBC Alumni Association awards 10 scholarships each year to community bankers.
Budget season is the perfect time to prioritize the training and development needs of your future leaders. As you make plans for the upcoming year, remember that the University of Sioux Falls is partnering with four graduate banking schools to offer their MBA with a banking concentration. Your future leaders can combine MBA coursework at USF with their work at one of the partnering graduate banking schools to complete their degree in less time with a targeted focus on banking.
Once you identify these future leaders, let them know that they can start the process now. By beginning with the USF MBA core classes, they will sharpen their skills in data analytics, explore leadership theory and learn more about leadership style, organizational culture and team dynamics. While their opportunity for graduate banking school may be a few years off, your commitment to their professional growth can start today.
For additional information on the program and investment, reach out to Lorri A. Halverson, director of graduate business programs, via email at [email protected].
The IRA Update builds on the attendees’ knowledge of IRA basics to address some of the more complex IRA issues their financial organizations may handle. This course includes how the SECURE Act really changes our two biggest topics: RMDs and death distributions and discusses any pending legislation. This is a specialty session; some previous IRA knowledge is assumed. The instructor uses real-world exercises to help participants apply information to job-related situations.
This course is designed as a “very basic” IRA seminar as it is designed to build a solid IRA foundation. The seminar will start with the differences between a Traditional and a Roth IRA, and then discuss how to set up a new IRA and the eligibility rules to contribute to an IRA. The biggest topic for people new to IRAs to discuss is the moving of money from one financial institution to another. This involves IRA transfers and rollovers, plus the direct rollovers from a qualified plan. Discussion will go through the 13 exceptions to taking money out of an IRA before age 59.5 to avoid the penalty tax, and how RMD is calculated in a traditional IRA. There will be an introduction into death distributions. Finally, we will cover how to take money out of a Roth IRA.
Next year's WIB Conference will be September 14-15, 2027! Watch your inbox for further details...
2027 Graduate School of Banking
July 18-29, 2027 | University of Wisconsin - Madison
GSB students acquire a broad knowledge and understanding of major bank functions and their interrelationships and develop the skills required to lead and manage effectively. The school’s curriculum reflects the contemporary trends impacting the financial services industry. Core courses address broad areas of finance, marketing, management and the environment in which banks operate while elective courses allow students to customize their learning experience. Graduates of the GSB program also receive the prestigious Executive Leadership Certificate from the Wisconsin School of Business Center for Professional and Executive Development — the highest level certificate they offer.
Over the course of 25 months, through a mix of lectures, bank simulations, case study discussions, and hands-on projects, you will learn to:
Retain your best customers
Increase your market share
Analyze market conditions to effectively manage risk
Achieve a sustainable competitive advantage
Utilize technology effectively to improve performance
Participating in learning opportunities outside the bank can be challenging. Take advantage of the SDBA's extensive selection of webinars and on-demand training to enhance your banking expertise directly from your computer.
Learn how to put compliance management solutions from Compliance Alliance to work for your bank, by contacting (888) 353-3933 or [email protected] and ask for our Membership Team. For timely compliance updates, subscribe to Bankers Alliance’s email newsletters.


 AI is crashing into the long-running fight between banks and financial technology companies.
 Consumers are happy with their credit cards and the benefits they offer, according to the results of


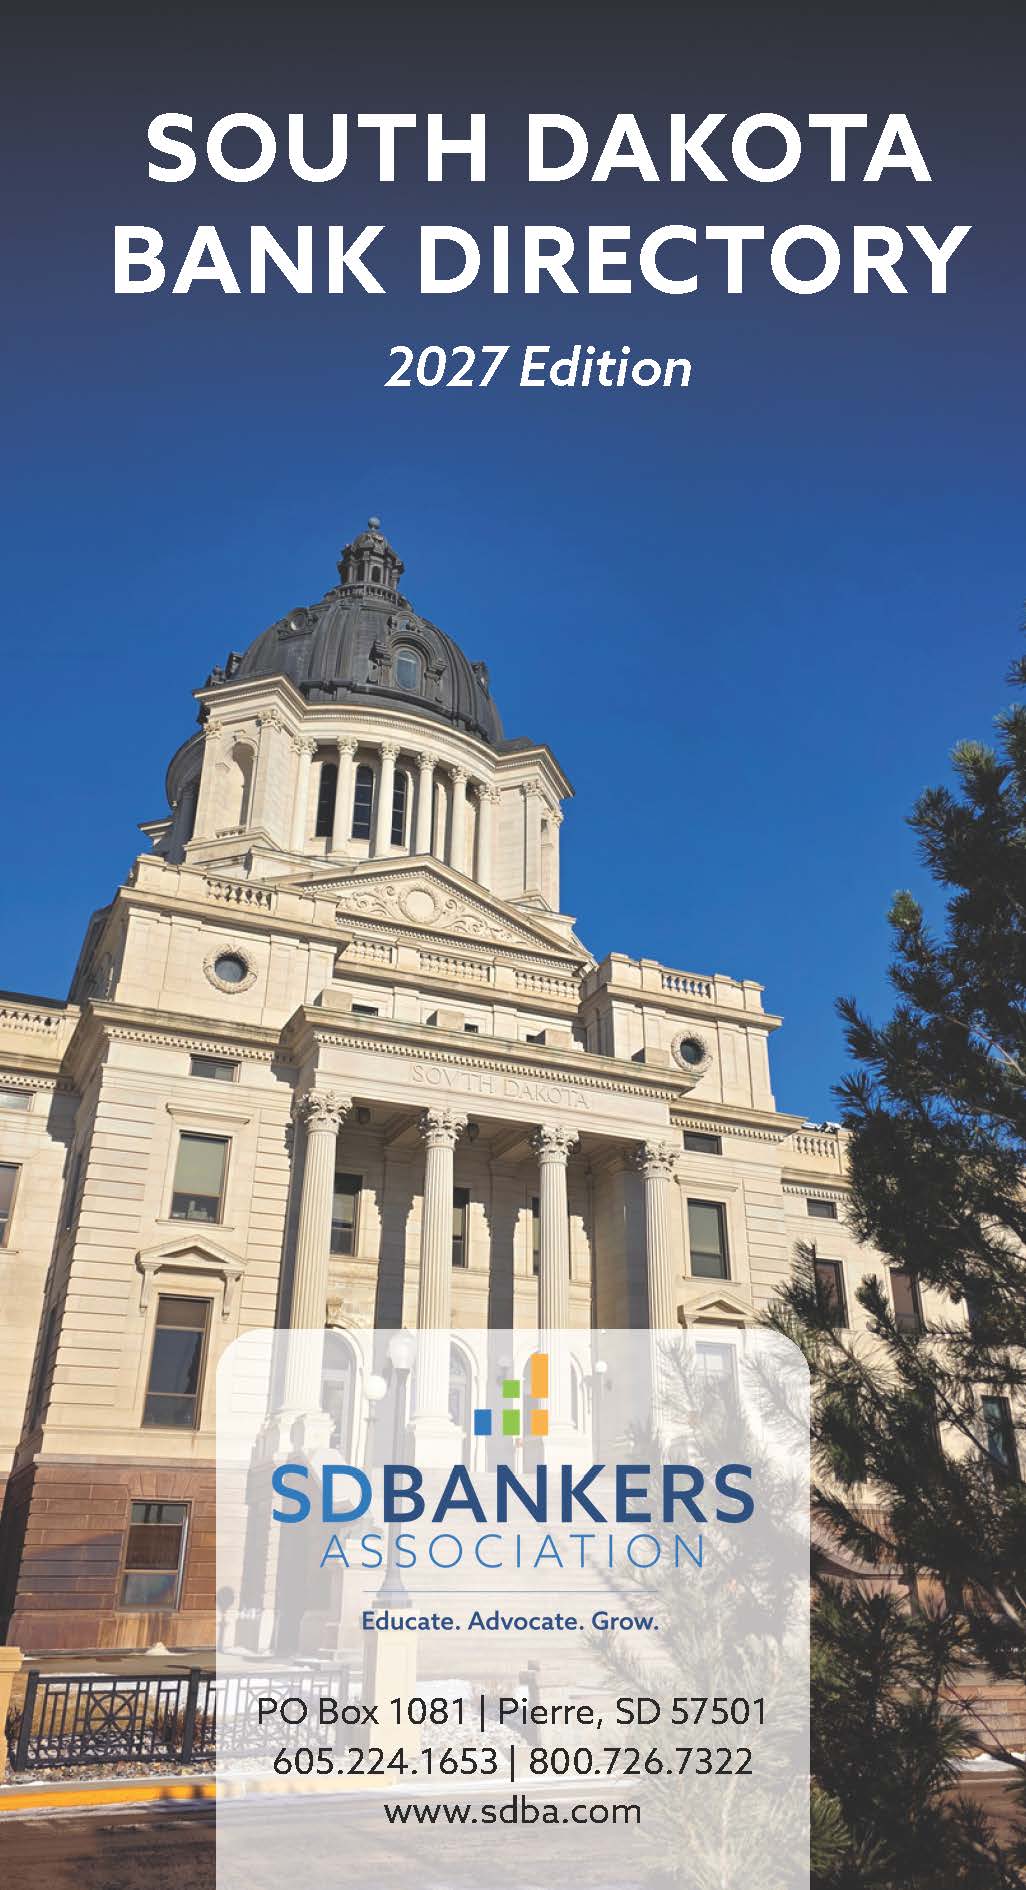 The South Dakota Bank Directory provides detailed information on all South Dakota banks including addresses, telephone numbers, important contact names and additional pertinent information. The directory also contains information on the SDBA, banking associations, regulatory agencies, endorsed vendors, associate members and South Dakota officials.

 Budget season is the perfect time to prioritize the training and development needs of your future leaders. As you make plans for the upcoming year, remember that the University of Sioux Falls is partnering with four graduate banking schools to offer their MBA with a banking concentration. Your future leaders can combine MBA coursework at USF with their work at one of the partnering graduate banking schools to complete their degree in less time with a targeted focus on banking.
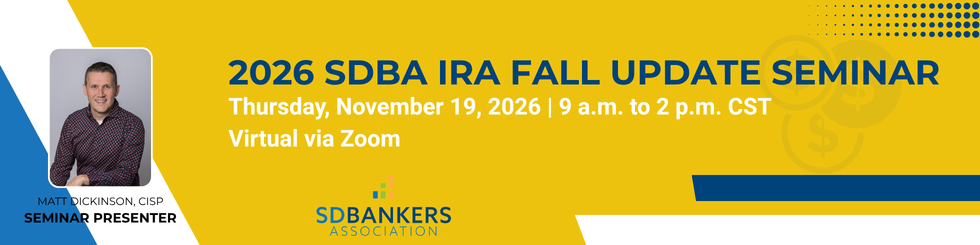

 SAVE THE DATE!
 GSB students acquire a broad knowledge and understanding of major bank functions and their interrelationships and develop the skills required to lead and manage effectively. The school’s

